Research
Working papers, methods and their limits.
Research uses public data, benchmarks and simulation, not measured real-loan losses. Ratings remain a goal, not an operating service.
Working papers
Papers
Base-model concentration and correlated loss across AI-agent operators
When many businesses run their agents on the same AI model, one failure of that model (an outage, a bad update, a price spike) can hit all of them at once. This paper asks whether that shared exposure can be measured before any losses happen. It shows that the concentration is measurable from public data, and measures it. Whether it predicts money lost is still an open question, and the paper says so.
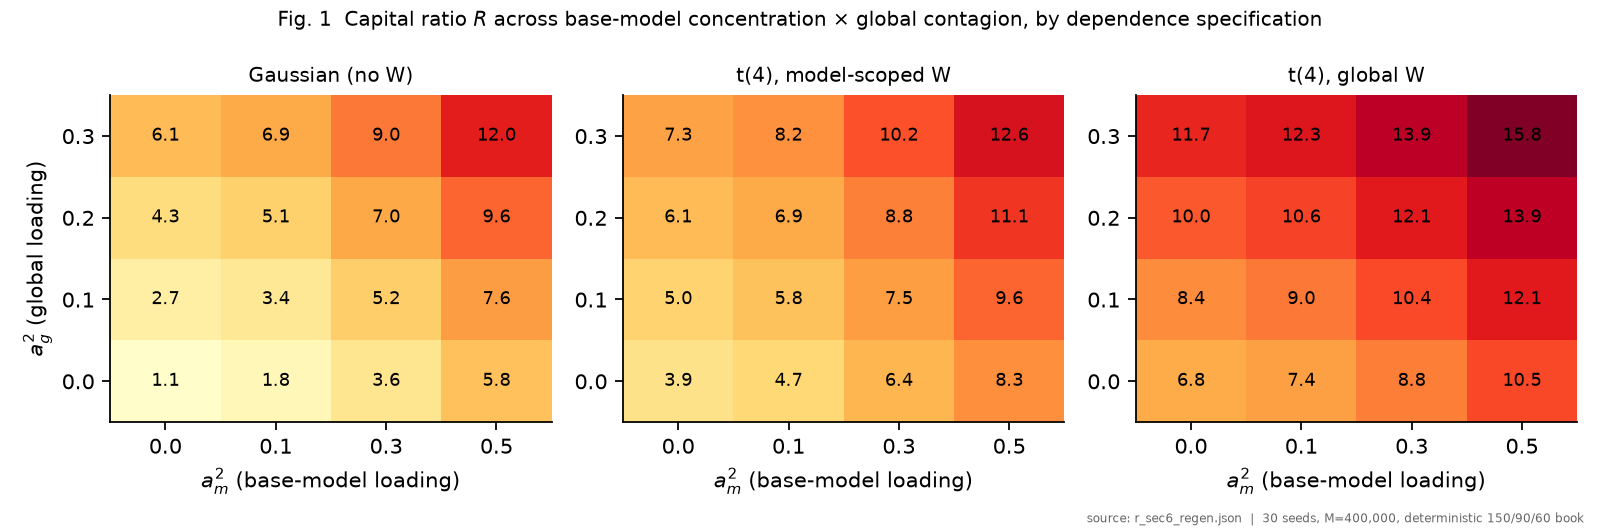 Open chart full size ↗
Further working papers, on underwriting and on credit control when the lender can act on each payment, are shared on request.
The research explores making per-payment control affordable for more borrowers. In the paper simulations, the modeled controls cut expected loss by about 5×.
This figure comes from the simulations in these papers. It has not been measured on real borrowers.
To read a paper, write to gaurav@reincredit.com.